
For tax, a vehicle is treated either as a van or as a car, and the label on the advert has nothing to do with it. A panel van is a van. A double-cab pickup used to be treated as a van if its payload was one tonne or more — but HMRC changed that test, and most double-cab pickups are now treated as cars when a benefit charge is worked out. VAT and road tax were not changed by that shift. If a vehicle is going to be provided to an employee, the classification is worth checking before you buy it, not after.
This guide sits under our VAT and tax guide, part of the Van Guides hub. It sets out the rules and points you at HMRC’s own words. It is not tax advice — your accountant is the person to settle your own position with.
Van or car? What a vehicle’s tax classification turns on
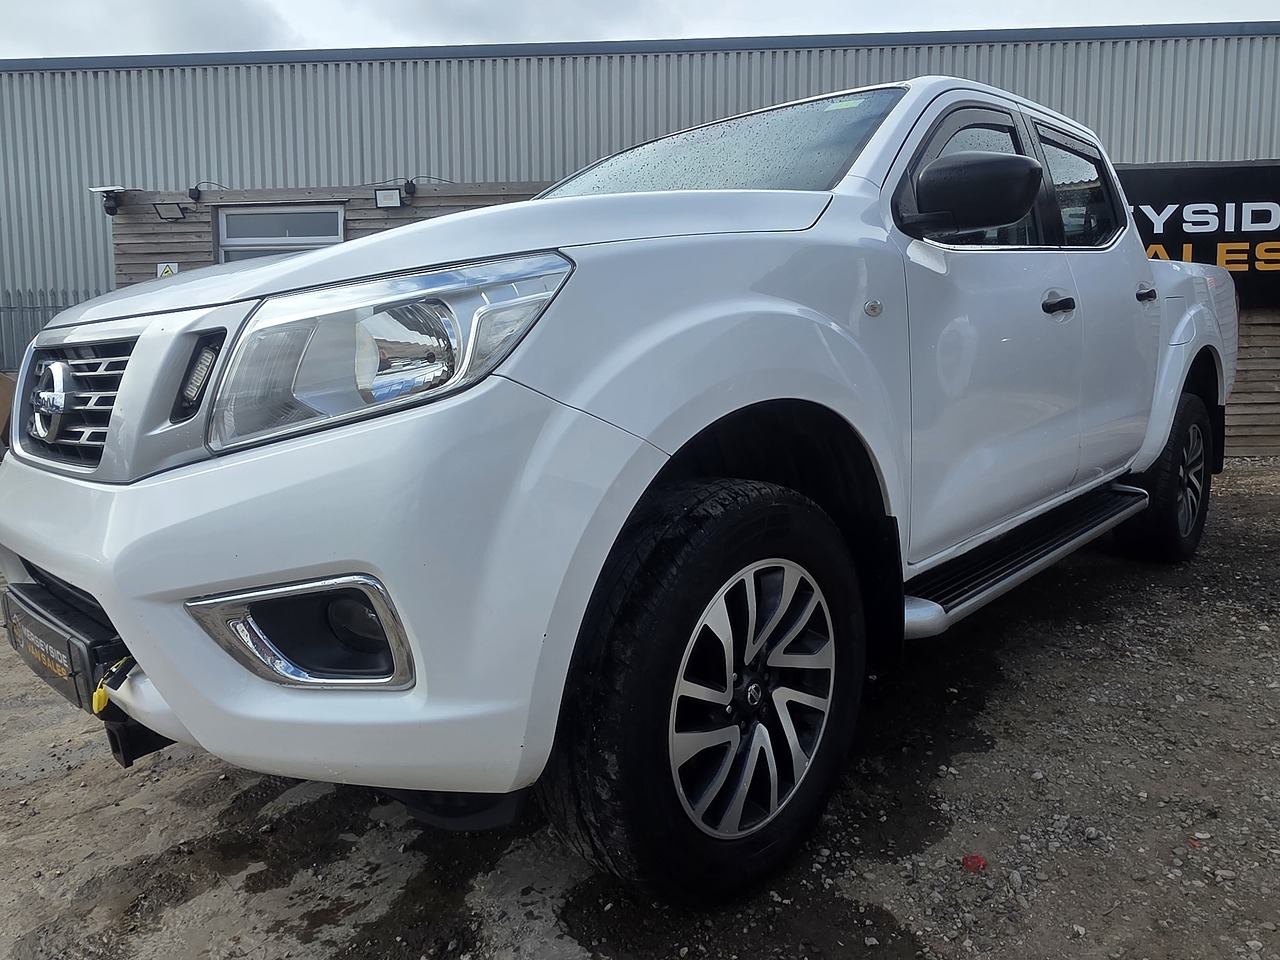
Three separate tax systems ask this question, and they do not all answer it the same way.
- Benefit in kind — the charge on an employee who has a vehicle provided by their employer. A van attracts a flat van benefit charge; a car attracts a charge based on list price and emissions, which is usually far higher.
- VAT — whether the VAT on the purchase can be recovered, which turns on a separate definition of a car.
- Vehicle excise duty — the road tax band, which uses its own vehicle categories again.
A vehicle can therefore be a van for one of those and a car for another, which is exactly why “is it a van?” has no single answer. The change described below affects the first of the three and leaves the other two alone.
Double-cab pickups and the one-tonne payload test
The old test was mechanical and easy to apply. HMRC’s own manual describes a double-cab pickup as a vehicle with a second row of seats and four doors, plus an uncovered load area — and set out that a double-cab pickup with a payload of one tonne or more was accepted as a van for benefits purposes.
Payload, in that test, is the gross vehicle weight minus the unoccupied kerb weight. Two details caught people out constantly:
- A hard top counts against you. HMRC’s guidance treats a hard top as weighing up to 45kg, and that comes off the payload — which is enough to push a vehicle sitting just over the line back under it.
- The figure is per specification, not per model name. Two pickups with the same badge can land on opposite sides of the test depending on trim, wheels and options.
If you need to check a weight rather than take one on trust, gov.uk explains the weight terms — maximum authorised mass, unladen weight and the rest — and the plate on the vehicle itself is where the real numbers live.
What changed for double-cab pickups, and who it affects
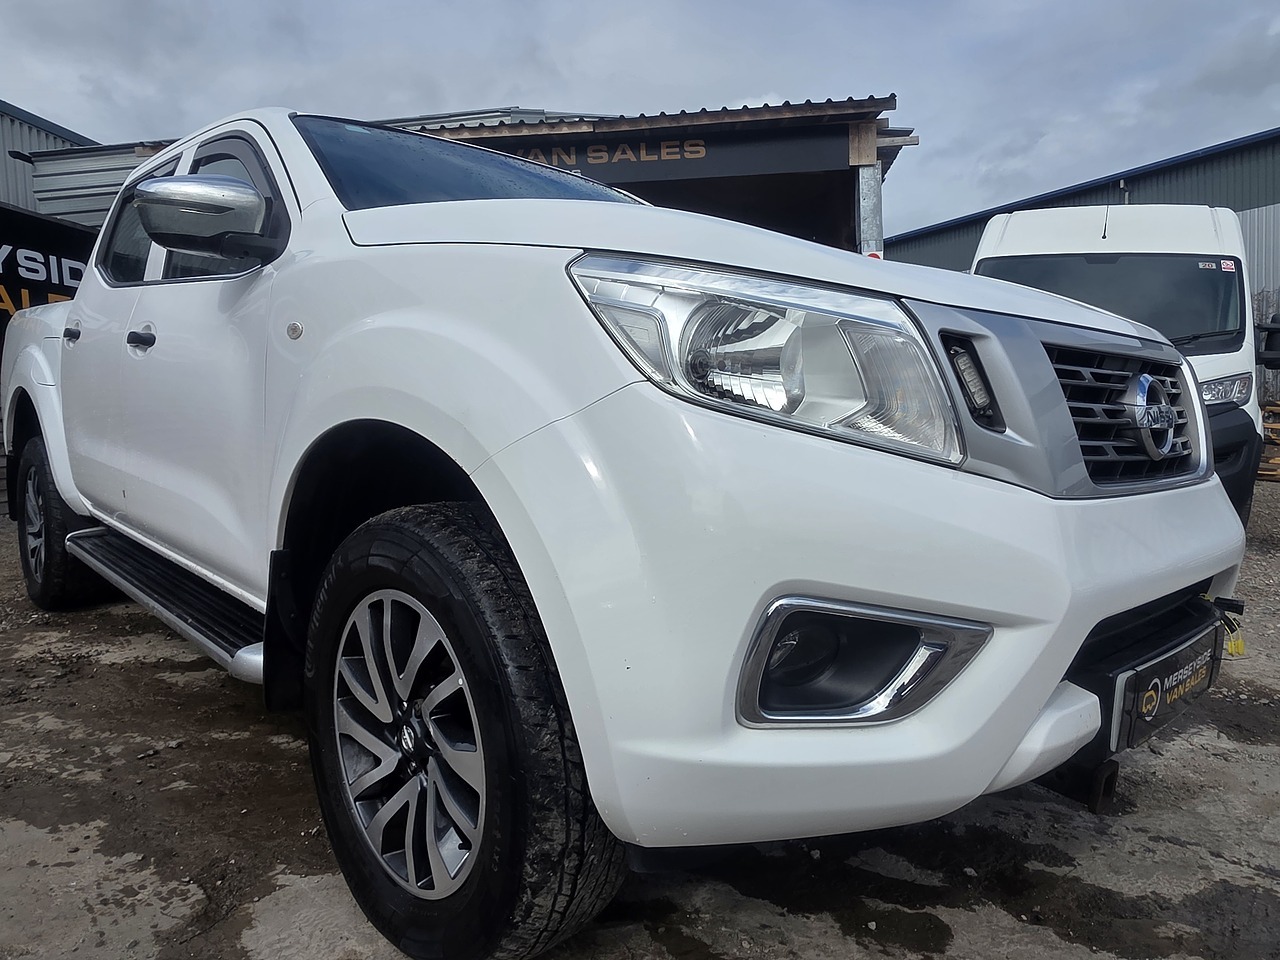
The payload threshold is no longer the test for the benefit charge. HMRC’s guidance for 6 April 2025 onwards says that most double-cab pickups are expected to be classified as cars when the benefit charge is calculated, because they are not predominantly suited to carrying goods. Where there is no clear predominant suitability, the vehicle defaults to being treated as a car.
Three things follow that are worth being clear about.
- It is the benefit charge only. HMRC’s own page says VAT and vehicle excise duty treatment are unchanged. Do not assume the pickup has moved boxes everywhere.
- There is transitional protection. Vehicles purchased, leased or ordered before 6 April 2025 can keep the previous treatment until the earlier of disposal, lease expiry, or 5 April 2029.
- It only bites where a vehicle is provided to somebody. A sole trader who owns their own pickup is not in benefit-in-kind territory at all — their question is about allowable expenses and capital allowances instead.
If a double-cab is on your shortlist for a member of staff, this is the single biggest cost difference between it and a panel van, and it will not show up anywhere on the advert.
VAT on vans and pickups: why that half did not change
VAT uses its own definition of a car, and commercial vehicles sit outside it. That is why the VAT position on a double-cab pickup was not disturbed by the benefit-charge change — the two systems were never reading from the same rule.
What decides whether you can recover VAT on any given vehicle is a separate question again, and one that depends on the vehicle’s own history as much as its shape. Our guide to reclaiming VAT on a used van covers it properly, and our explainer on no-VAT vans covers why some vehicles carry no reclaimable VAT at all.
Crew cab vans and combi vans: same shape, different question
A crew cab van and a combi van have the same basic layout as a double-cab pickup — a second row of seats, then a load area — but the load area is enclosed rather than open. That difference matters, because the current benefit-charge test is about what the vehicle is primarily suited to, and an enclosed load bay behind a bulkhead points more clearly at goods.
That is a general observation and not a ruling on your vehicle. Seat count, window arrangement, bulkhead and payload all feed into it, and two vans that look similar on a forecourt can be assessed differently. If a crew cab is going to be provided to staff, get it checked on its own facts.
Used double cab vans for sale: what to check before you buy
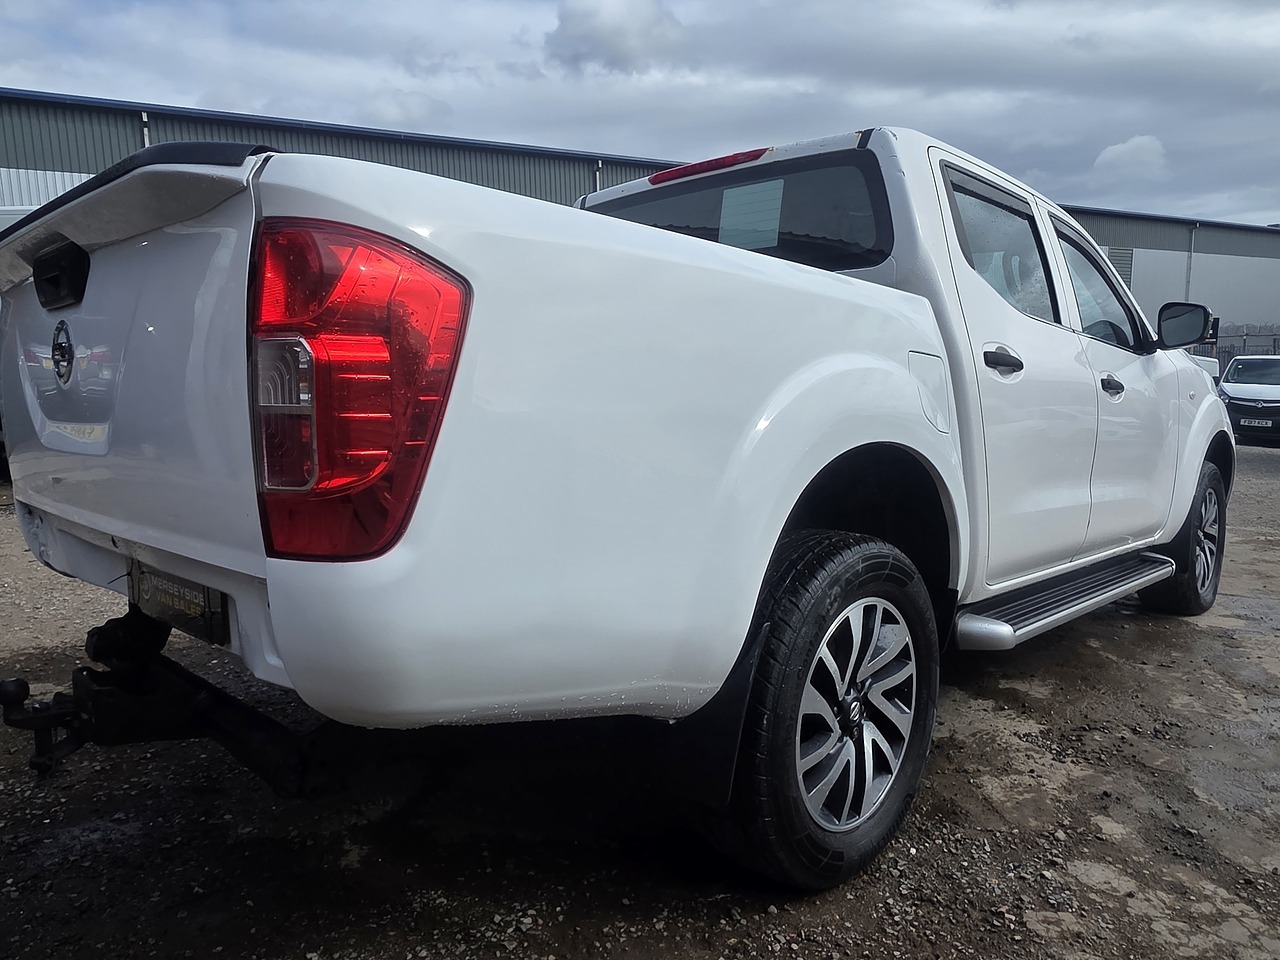
Five things to establish about a specific vehicle before you commit to it:
- Its gross vehicle weight and kerb weight, from the plate on the vehicle rather than from a brochure.
- Whether a hard top or canopy is fitted, and whether it was on the vehicle when it was first registered.
- When it was first ordered, bought or leased — that date is what decides whether transitional protection applies.
- Its VAT status — whether it is sold under the margin scheme or plus VAT.
- Who is going to be driving it, because the benefit charge only arises where a vehicle is provided to somebody.
Here is where our own experience does and does not help. More than three-quarters of everything we sell is a small or medium panel van, so panel vans are what we can speak about with any authority. We have sold too few pickups to publish a statistic about them, and we would rather say that than dress up a handful of sales as a pattern. On the classification question, HMRC’s manual and your accountant are the authorities — not a van dealer.
If you are not sure how a vehicle is classified
Work through it in this order, and it stays simple.
- Which tax are you actually asking about? Benefit in kind, VAT and road tax have different answers.
- Is the vehicle being provided to somebody, or owned by the person using it? If nobody is being provided with it, the benefit charge does not arise.
- Get the vehicle’s own weights and dates, not the model’s.
- Put those facts to your accountant, or check them against HMRC’s manual directly.
If it turns out a panel van suits you better after all, see what we have in stock now, and our guide to choosing the right van is the place to work out what size you need.
Common questions
Is a double-cab pickup a van or a car for tax?
For the benefit charge, HMRC’s guidance for 6 April 2025 onwards expects most double-cab pickups to be treated as cars, because they are not predominantly suited to carrying goods. For VAT and road tax, nothing changed. So the honest answer is that it depends which tax you are asking about.
Does the one-tonne payload rule still apply?
Not as the test for the benefit charge. It was replaced by a primary-suitability test, and a vehicle with no clear predominant suitability now defaults to car treatment. Payload still matters for plenty of other reasons — what the vehicle can legally carry being the obvious one — but it no longer settles the classification question.
I bought my pickup before the change. Am I affected?
There is transitional protection for vehicles purchased, leased or ordered before 6 April 2025. Under it the previous treatment can continue until the earlier of disposal, lease expiry, or 5 April 2029. The date the vehicle was ordered matters as much as the date it arrived, so dig out the paperwork rather than working from memory.
Does this affect me if I am self-employed and own the pickup myself?
Not for benefit in kind, because there is no employer providing you with a vehicle. Your questions are about allowable expenses, capital allowances and the VAT position instead — all of which have their own rules, and all of which your accountant is better placed to answer than any dealer.
Where can I check a specific vehicle’s payload?
On the vehicle itself. The plate fixed to the vehicle carries its gross weight, and the payload is that figure minus the unoccupied kerb weight. Do not take a payload from a brochure or an advert: trim, wheels and fitted equipment all move it, and a fitted hard top counts against it.