
Before you apply for van finance, have four things ready: photo ID and proof of your address, three to six months of bank statements, evidence of what you earn or what your business turns over, and the details of the van itself. That is the core of nearly every application, whether you are a sole trader, a limited company or buying in your own name. Gather them first and the application takes minutes rather than days — and you spend that time answering questions rather than hunting for paperwork.
Merseyside Van Sales is a credit broker, not a lender. Finance is subject to status and affordability checks, and is available to over-18s only. A representative example is available on request. Figures quoted are illustrative and do not constitute an offer of finance.
This guide sits under our Van Finance guide, part of the Van Guides hub. It deliberately quotes no rate and no repayment figure anywhere — those are worked out against your circumstances and a specific van, and a number printed on a page like this one is out of date within weeks.
What you need before you apply for van finance
Most applications ask the same four things, in roughly this order.
- Who you are. A current photo driving licence or passport, and an address history going back three years. Gaps and recent moves are the commonest reason an application stalls, so write the dates down before you start.
- What you earn. For an employee, recent payslips. For a sole trader, accounts or self-assessment figures. For a limited company, filed accounts or management figures.
- What your bank account looks like. Three to six months of statements is the usual ask. Lenders read them for income going in and for regular commitments going out — not for judgement about your shopping.
- Which van. The specific vehicle, its price and any deposit or part-exchange. Finance is arranged against a van, not in the abstract, so a shortlist of two or three is more useful than a general enquiry.
None of that is a promise about the outcome. It is simply what the form asks for, and having it to hand is the difference between one conversation and four.
The documents a lender will ask for
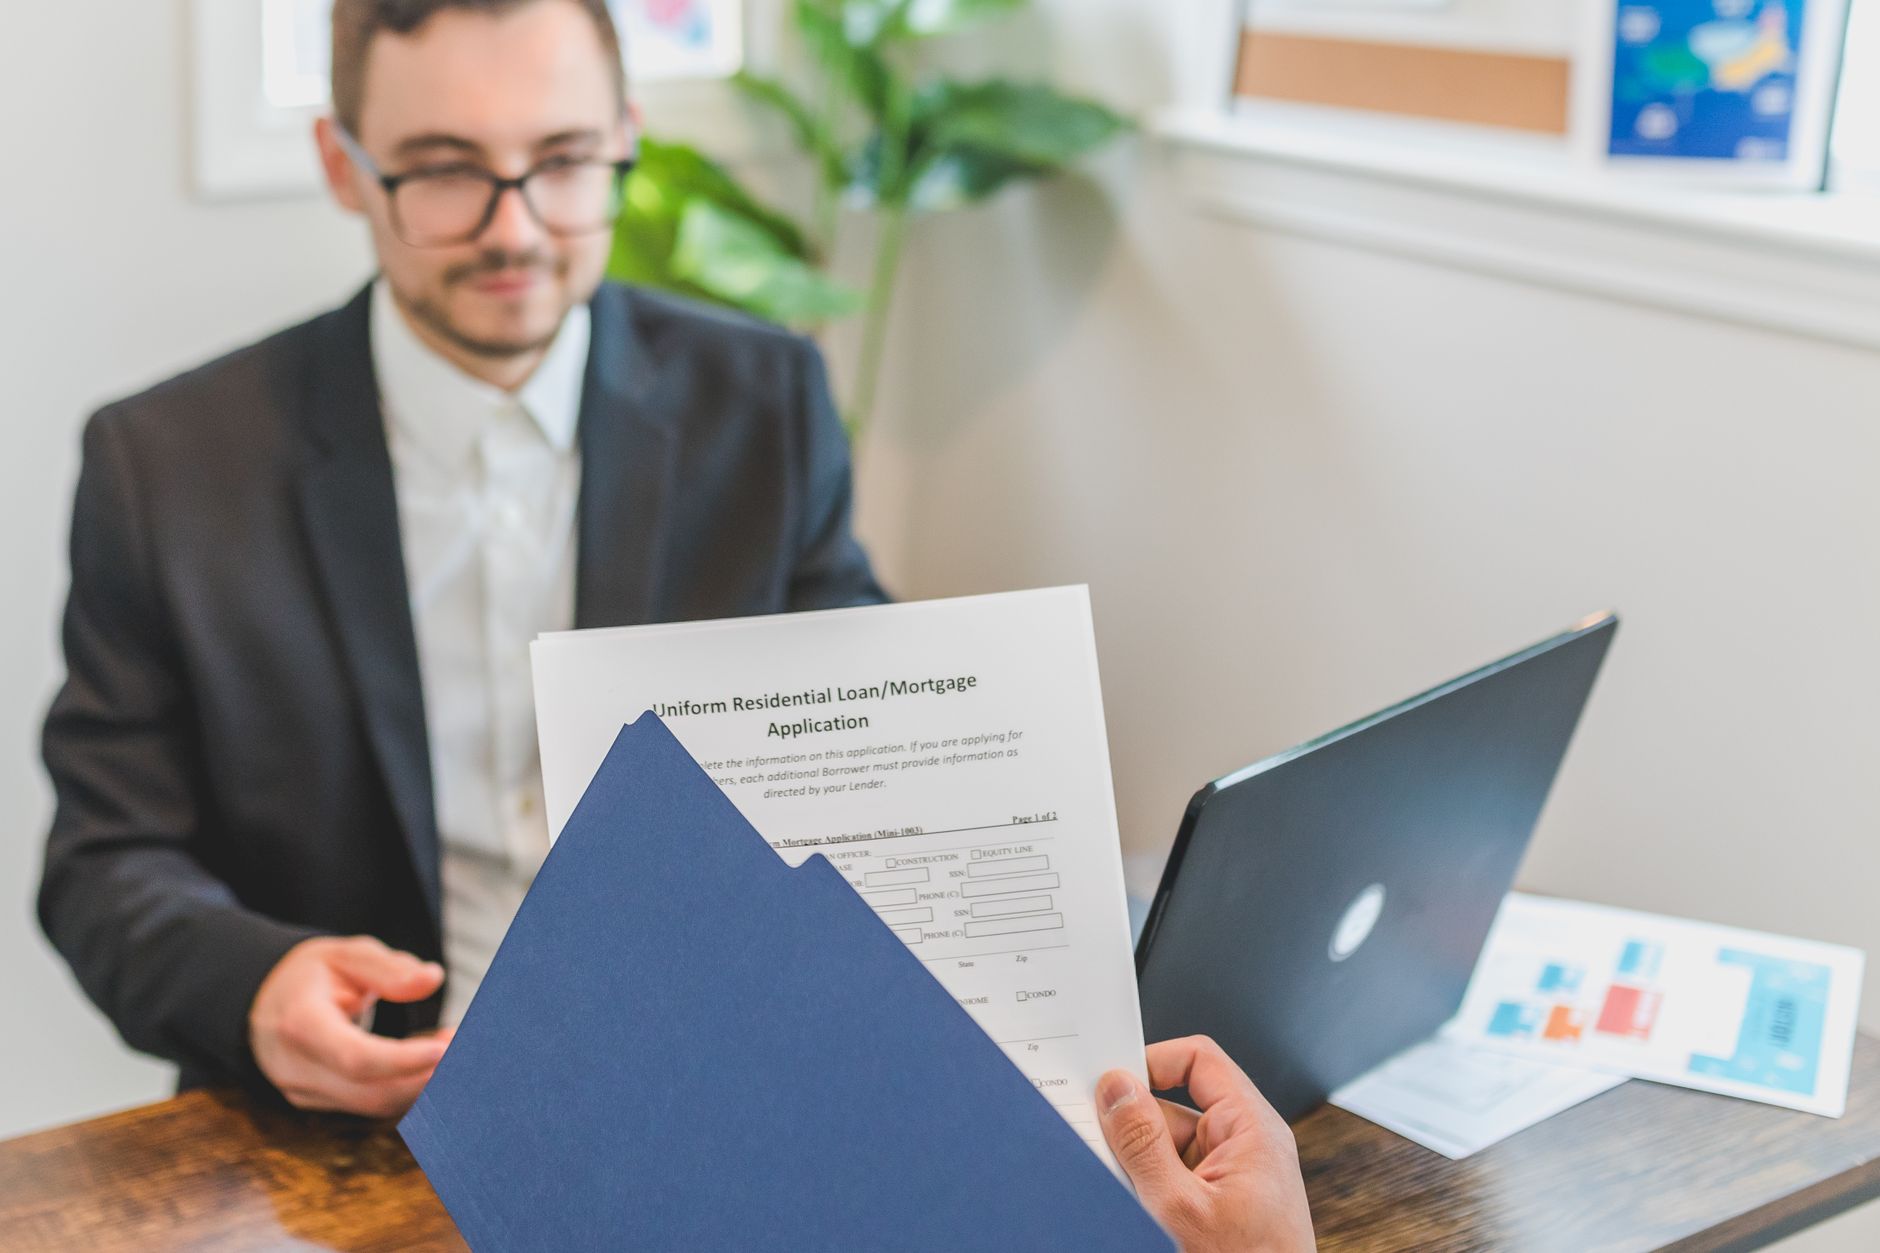
The exact list varies by lender and by the type of agreement, but the pattern is consistent:
- Proof of identity — photo driving licence or passport, in your current name.
- Proof of address — a utility bill, council tax bill or bank statement, usually dated within the last three months. Your driving licence address must match.
- Address history — three years of it, with the dates.
- Proof of income — payslips, accounts, or self-assessment paperwork depending on how you are paid.
- Bank statements — normally three to six months, for the account your income lands in.
- Business details, if the agreement is a business one — trading name, company number, VAT registration if you have one, and how long you have traded.
- Proof of insurance — usually needed before the van is handed over rather than at application.
A tip worth more than it sounds: send clear, complete copies the first time. A partly legible statement or a bill three days outside the date window is the commonest cause of a decision taking two days instead of two hours.
What “subject to status” actually means
Every honest finance page carries the phrase, and it is worth translating. It means the lender decides, after looking at your circumstances, and that decision has not been made yet. It is not a warning and it is not a reassurance — it is a statement that nobody, including us, knows the answer before the application is looked at.
Two things follow from that. First, no one can tell you in advance what you will be offered, or whether you will be offered anything. Anyone who does is guessing. Second, “affordability” is a separate test from credit history: a lender is checking that the repayments fit alongside your existing commitments, not only that you have paid things on time in the past.
If your credit file has something on it you already know about, say so early. It is much better raised at the start than discovered halfway through.
Sole trader, limited company or personal: which application is which
Which shape of application you make changes what gets asked for, and it is worth settling before you start rather than halfway down a form.
- Personal. The agreement is in your own name and assessed against your own income and credit history. Straightforward, and the right route if the van is not for a business.
- Sole trader. Legally still you, so your personal credit history matters — but the lender will also want to see the trade: accounts, self-assessment, or invoices if you are newer than that.
- Limited company. The agreement sits with the company, assessed on filed accounts and trading history. A director’s guarantee is common, particularly on a younger company, which puts your personal position back in the picture.
There is a tax dimension to the choice as well. A van bought for a business may qualify for capital allowances, which is a genuine consideration and not one this page can answer for you — gov.uk sets out how capital allowances work, and your accountant will know how they apply to you. The VAT position is a separate question again: our guide to reclaiming VAT on a used van covers it properly, and our VAT and tax guide gives the wider picture.
What happens after you apply
The sequence is much the same everywhere.
- The application goes to a lender — or to more than one, which is part of what a broker does.
- A decision comes back. Often quickly. Sometimes it comes back with a question attached, which is normal rather than a bad sign.
- The offer is set out in writing — the agreement type, the term, what you pay and when, and what happens at the end. Read the end of the agreement as carefully as the beginning; hire purchase and leasing finish very differently.
- You sign, and the van is prepared. Insurance needs to be in place before you drive away.
Nothing is binding until you sign, and the written agreement is the thing that counts — not a conversation, not an email summary, and not a page like this one.
Where finance sits against paying cash
Neither is right in general. Cash costs nothing to borrow and leaves you with the van outright; finance keeps working capital in the business and spreads the cost, at a cost. Which matters more depends on what else that money would be doing.
What we can tell you is what has changed around us. Three years ago about one buyer in five put a van on finance with us. Now it is closer to one in three. That is not us pushing it — it is what has happened to the price of a working van. We are describing what customers have done, not recommending that you join them.
The rules around business vehicle finance and tax do shift from year to year; this update covers the most recent changes. If you are still deciding what to buy at all, our guide to buying a van is the better starting point.
Vans on finance near me: what a local dealer can and cannot do
A local dealer can show you the actual van, put a realistic figure on your part-exchange, and pass a complete application to a lender that already knows the sort of vehicles we sell. What a dealer cannot do is approve you, quote you a rate, or tell you what your repayments will be before an application has been assessed.
That distinction has a name. Merseyside Van Sales is a credit broker, not a lender — we introduce you to finance providers; they make the decision and they hold the agreement. It is worth checking anyone you deal with, us included, on the FCA’s Financial Services Register, which lists every firm authorised to broker or provide consumer credit in the UK.
Merseyside Van Sales is a credit broker, not a lender. Finance is subject to status and affordability checks, and is available to over-18s only. A representative example is available on request. Figures quoted are illustrative and do not constitute an offer of finance.
When you are ready for an actual figure rather than an explanation, our van finance page is the one built to take a real enquiry. And if you would rather find the van first, see what we have in stock now — the application is easier when it has a specific vehicle attached to it.
Common questions
Will applying for van finance affect my credit score?
A full application leaves a hard search on your file, which other lenders can see. Many providers can run a soft check first, which does not. If you would rather not leave a mark before you are ready, ask whether a soft search is available and make that clear at the start rather than after the form has gone.
Can I get van finance as a new business with no accounts?
It is harder, not impossible. Lenders want evidence the business can support the repayments, and trading history is the usual evidence. Without it, a strong personal credit history, a director’s guarantee or a larger deposit can all count. Take whatever you do have — early invoices, a signed contract, a book of work.
Do I need a deposit?
It depends on the agreement. A deposit reduces what you borrow, and it is asked for more often on hire purchase than on some lease structures. What it does not do is decide the outcome — a bigger deposit does not by itself change whether an application is accepted or what type of agreement is offered.
Can a part-exchange count as the deposit?
Usually, yes. The agreed value of your old van is normally applied towards the deposit rather than paid out to you separately. Get the part-exchange valued before the application goes in, so the figures on the form are the real ones and nothing has to be redone later.
How long does a decision take?
Often the same day, sometimes within the hour, occasionally longer if the lender comes back with a question. The single biggest thing in your control is the quality of what you send: complete, in-date, legible documents move faster than any amount of chasing.